A refused or reduced kasko flood claim should first be analysed by the reason for the dispute. Missing cover, an alleged driver error, a disputed technical cause, low valuation and an excess deduction need different evidence. In Türkiye, insurance arbitration, court proceedings and mediation can have different roles. There is no single procedure appropriate to every policyholder.
Obtain a clear written refusal
Short explanations such as “water entered the engine” or “user error” do not answer every coverage question. Ask which policy clause is relied on, which technical finding supports the conclusion and what documents remain missing. Confirm telephone discussions in dated correspondence. Compare the policy, workshop diagnosis and expert report against one consistent event timeline.
Separate the cause of damage from policy interpretation
Whether water caused damage while parked, while driving or after a restart can matter. That does not mean every driver who encounters water is automatically at fault. If poor maintenance or a manufacturing defect is alleged, examine the technical basis. Flood cover does not necessarily include every claimed expense, but exclusions also need to be applied to the actual facts rather than treated as a blanket slogan.
Make a documented request to the insurer
State the disputed items, requested amount where established and supporting evidence in writing. Preserve delivery records and the insurer’s reply. The first incident notification and a later fully formulated compensation request may have different contents. A useful objection explains why a particular refusal or calculation is wrong rather than simply expressing dissatisfaction.
When can insurance arbitration be considered?
The Insurance Arbitration Commission states that an unsatisfactory final response, or no written response within fifteen working days in a kasko dispute, can support an application subject to its other conditions. Do not confuse this with the fifteen-day rule for compulsory traffic insurance. For voluntary kasko, check the insurer’s membership and whether the insured event occurred after the relevant membership date. Current fees, objection thresholds and appeal rules must be checked when filing.
Court jurisdiction and mediation depend on the transaction
Consumer and commercial transactions may lead to different courts and pre-action requirements. Article 73/A of Law No. 6502, Article 5/A of the Turkish Commercial Code and applicable exceptions must be considered, together with any consumer-board jurisdiction. Insurance arbitration is a separate procedure from a court claim. Starting the same dispute simultaneously through several routes can create admissibility problems.
Prepare a reviewable file
- Policy, endorsements, claim number and written demand.
- Proof of delivery and the final response, if any.
- Expert and workshop reports, photographs and event timeline.
- Separate repair, market value, excess, salvage and payment calculations.
- Settlement releases and any lender or lease interests.
- Dates relevant to limitation, default interest and procedural steps.
A regulatory complaint is not a compensation judgment
A complaint to SEDDK, an internal appeal, arbitration and litigation perform different functions. Do not assume that a complaint awards money or suspends every time limit. Statutory limitation, including Article 1420 of the Turkish Commercial Code where applicable, needs separate review. A lawyer can audit the evidence, formulate technical and legal objections, calculate the claim and select an appropriate route; no outcome can be guaranteed.
Frequently asked questions
Must I wait fifteen working days after a final rejection?
An existing unsatisfactory final response can be assessed under the Commission’s rules without treating the waiting period as the only gateway.
Is arbitration available against every kasko insurer?
Membership and event-date conditions matter for voluntary insurance; do not import compulsory traffic-insurance exceptions into kasko.
Does instructing a lawyer guarantee payment?
No. Legal review can improve preparation and representation but cannot guarantee an insurer’s, arbitrator’s or court’s decision.
DISCUSS YOUR CASE
Review a flood insurance refusal or underpayment
We can review the insurer’s reasons, policy terms and possible arbitration or court routes to assess your options under Turkish law.
A brief summary and important dates are enough for an initial enquiry. Send documents only when requested by our lawyers, through the channel they specify. Do not share passwords, one-time codes or wallet keys.
Related guides
- Flooded Car in Türkiye: Kasko Notification, Evidence and Payment
- Uninsured Flood-Damaged Car: Claims Against Public Authorities in Türkiye
- Flood Total Loss: Market Value, Salvage and Settlement Releases in Türkiye
- Car Flooded in a Car Park, Residential Complex or Mall: Who May Be Liable?
- Electric vehicle flooding and battery damage
Official sources
- Sigorta Tahkim Komisyonu: Başvuru Nasıl Yapılır?
- Sigorta Tahkim Komisyonu: Başvuruda İstenen Belgeler
- 6102 sayılı Türk Ticaret Kanunu: m. 1420, 1427, 1446, 1448 ve 1472
- 6502 sayılı Tüketicinin Korunması Hakkında Kanun: m. 73 ve 73/A
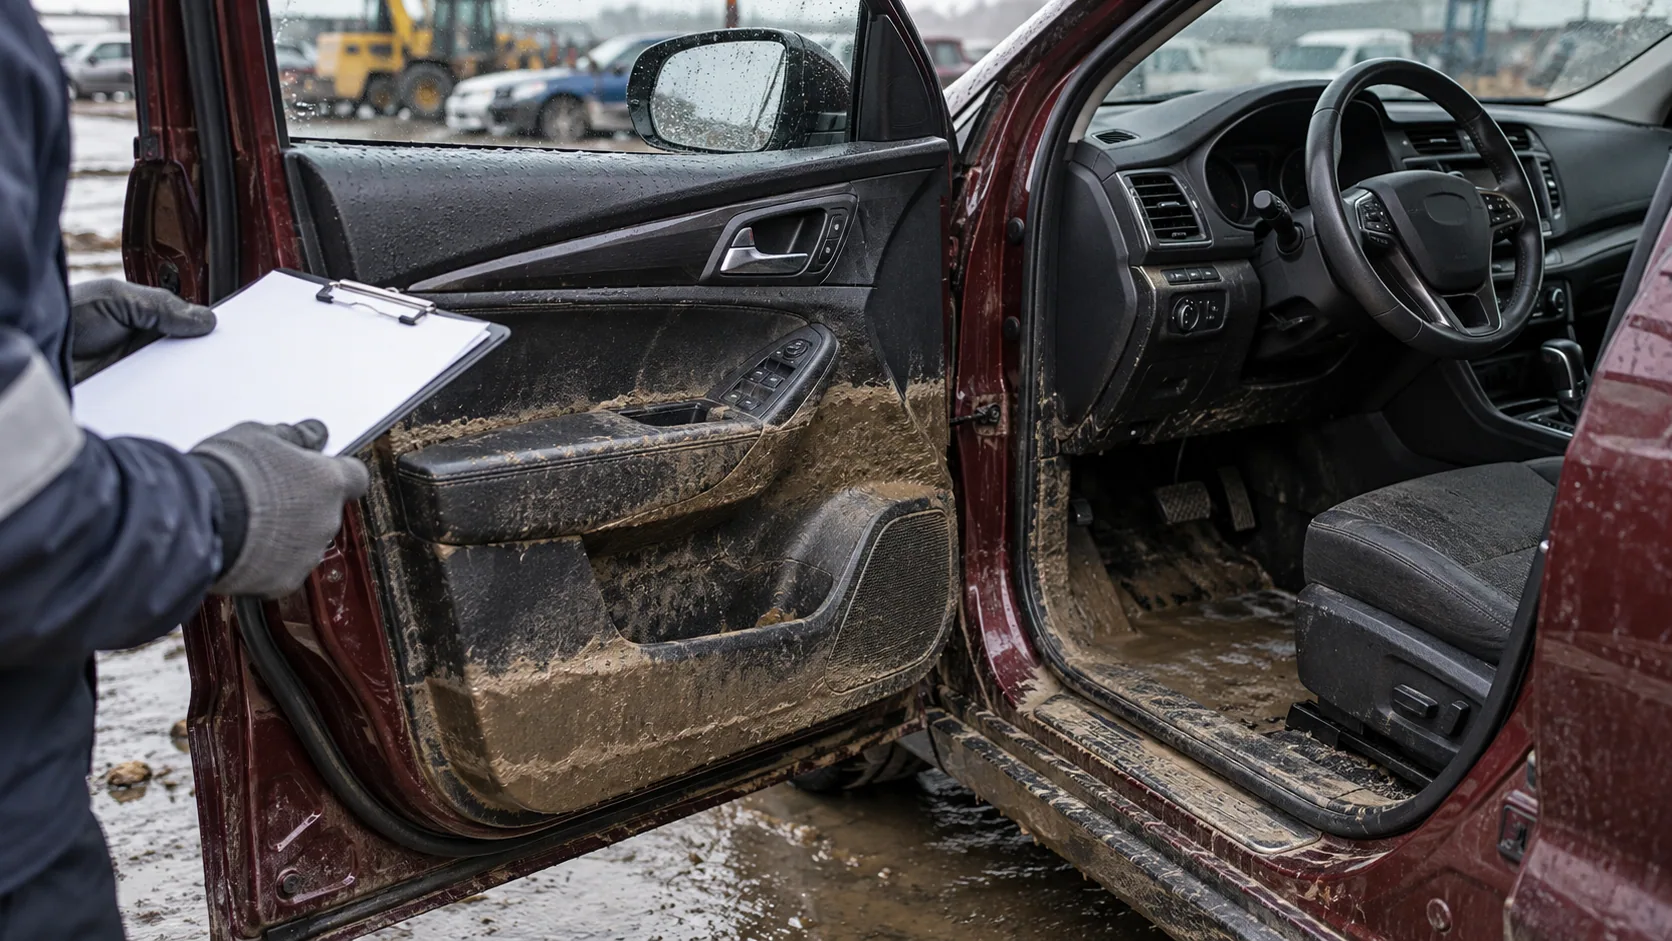
Updated: 15 October 2026. General information on Turkish law. The policy and evidence determine the assessment in each case. Image is illustrative.