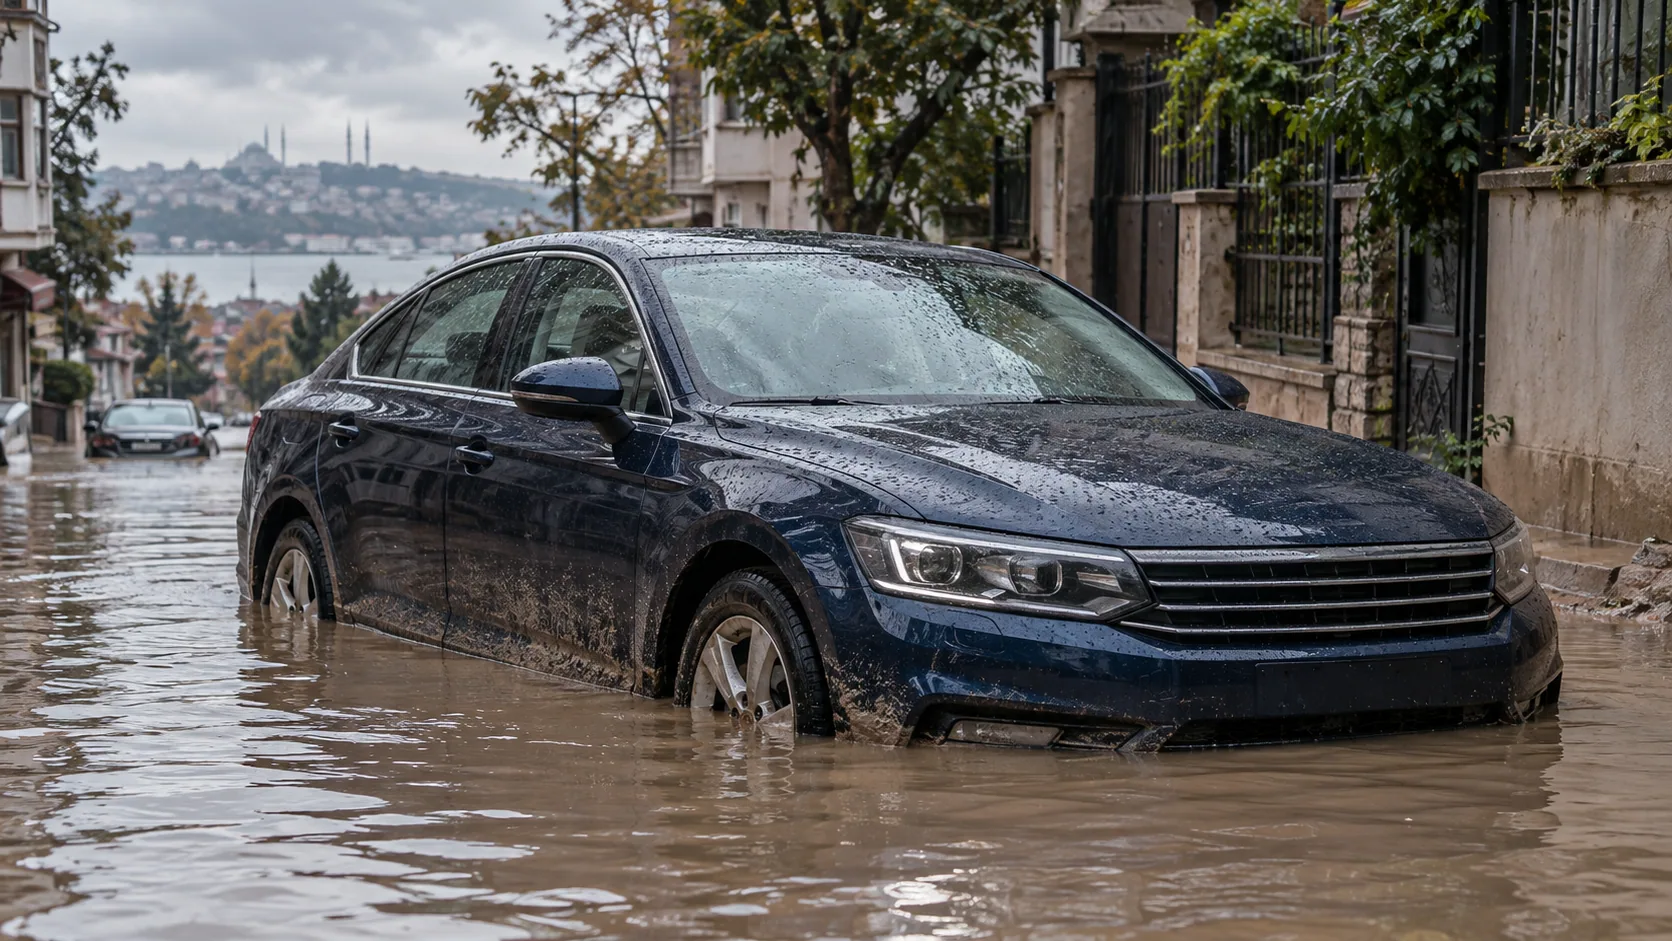
A car left underwater after heavy rain in Istanbul raises several different questions: whether the policy covers flooding, which damage was caused by water, whether repair is safe, and what evidence the insurer needs. Having a policy called “kasko” does not answer all of them. This guide concerns Turkish law and comprehensive motor insurance in Türkiye; it is not a guide to insurance rules in the UK, the US or another country.
Check flood cover, not just the product name
Compulsory motor third-party liability insurance is not general cover for your own car’s flood damage. Kasko may cover the vehicle within the risks actually insured. Flood and inundation appear under the additional-cover provisions of the Turkish Kasko General Conditions. Read the schedule, endorsements, excess, exclusions, insured use, vehicle details and policy start time. A renewal or product label is not a substitute for the actual contract.
Notification: five working days from learning of the event
Section B.1.1 of the General Conditions requires notification no later than five working days after learning that the insured event occurred. Notify promptly once safe; do not treat this as permission to wait. Keep the claim reference and dated email, app receipt or other record. Late notification does not automatically produce the same total loss of rights in every case: fault and any increase in the insurer’s payment require assessment under Turkish Commercial Code Article 1446. Explain a delay honestly and preserve supporting evidence.
Protect people, the vehicle and the evidence
Do not attempt to start a submerged car or charge a flooded electric vehicle. Use qualified recovery and workshop assistance. Where safe, preserve photographs showing water level, position, surrounding drainage and the time sequence. Emergency safety action takes priority, but record why dismantling, moving or disposing of parts was necessary. Unrecorded repairs can remove evidence needed to distinguish flood damage from an unrelated mechanical defect.
Prepare one organised claim file
- Policy, endorsements, registration document and claim reference.
- Date, time, exact location, photographs and available video.
- Any fire service, police, municipal or recovery report.
- Recovery invoices, workshop intake, diagnostic report and itemised repair estimate.
- Expert report, insurer’s document requests and delivery records.
- Written refusal or settlement offer, including the excess calculation.
Separate repair, total loss and additional expenses
Opening a claim file does not mean every item is accepted. Repair cost, pre-loss market value, excess and the remaining vehicle’s value are different figures. Payment timing depends on the policy, required documents, assessment and the applicable statutory rules; a single unconditional payment date cannot be promised for every case. Replacement transport, loss of use and business interruption must have their own policy or liability basis. If the car is financed, leased or subject to a lender’s interest, check who is entitled to receive payment.
A practical example
Two cars may be affected by the same water level but have different files. One was parked and recovered without being started; the other was driven and later restarted. That difference is a question for evidence and technical assessment, not an automatic conclusion of fault. Record the sequence instead of adapting your account to what you think the policy requires.
What can legal assistance cover?
A lawyer can compare the refusal with the policy, identify missing evidence, review valuation and deductions, assess whether court-assisted preservation of evidence is needed, and select an appropriate dispute route. Potential claims against a public authority or car-park operator should be coordinated with the insurance claim. The same loss cannot be recovered twice. Initial enquiries should contain a short summary and relevant dates; send documents only when requested by our lawyers through the channel they specify.
Frequently asked questions
Does kasko definitely pay if the car was parked?
Parking alone does not establish cover. The flood endorsement, exclusions, excess and technical connection between the event and damage still matter.
The workshop has dismantled the car. Is a claim impossible?
Not necessarily. Existing diagnostics, photographs and dismantling records need review. Preserve the date, reason and parts records.
Do I have to send identification documents in the first enquiry?
No. Start with a brief summary and dates. Documents should be provided only when requested through the specified contact channel.
DISCUSS YOUR CASE
Discuss your flood insurance claim
We can review policy coverage, claim notification and the insurer’s response to assess your options under Turkish law.
A brief summary and important dates are enough for an initial enquiry. Send documents only when requested by our lawyers, through the channel they specify. Do not share passwords, one-time codes or wallet keys.
Related guides
- Uninsured Flood-Damaged Car: Claims Against Public Authorities in Türkiye
- Flood Total Loss: Market Value, Salvage and Settlement Releases in Türkiye
- Kasko Refuses Flood Damage: Arbitration, Mediation and Court Options
- Car Flooded in a Car Park, Residential Complex or Mall: Who May Be Liable?
- Electric vehicle flooding and battery damage
Official sources
- Kara Araçları Kasko Sigortası Genel Şartları
- 6102 sayılı Türk Ticaret Kanunu: m. 1420, 1427, 1446, 1448 ve 1472
Updated: 15 October 2026. General information on Turkish law. The policy and evidence determine the assessment in each case. Image is illustrative.