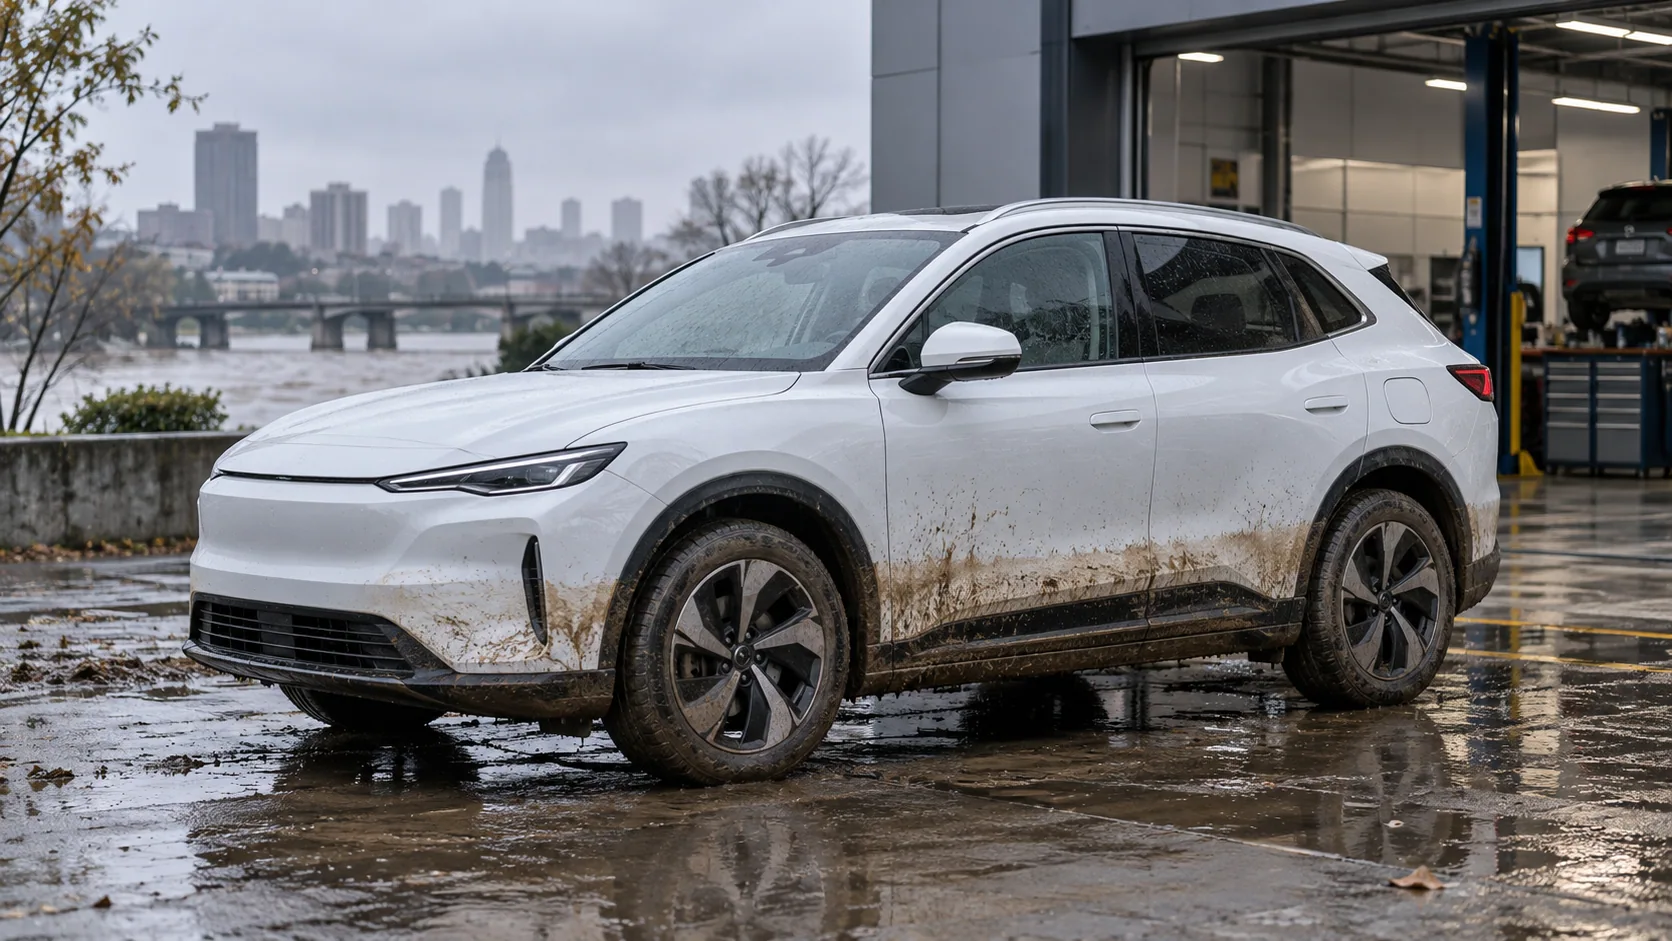
Battery failure after flooding can create substantial repair costs for an electric vehicle. Whether Turkish comprehensive motor insurance responds depends on the policy cover, cause of damage and technical evidence, rather than the fact that the car is electric alone.
Check the actual flood cover first
Read how flood and water damage are covered, including endorsements, excesses and exclusions. Comprehensive policies do not all provide identical protection. The battery’s position within the vehicle, electric-vehicle conditions and cover for connected equipment may also matter.
Distinguish water damage from a manufacturing defect
Sudden flooding, wear, manufacturing defects, inadequate maintenance and earlier faults require different assessments. A brief workshop entry saying ‘battery failure’ may not establish the cause. The point of water ingress, diagnostic logs, event timing and the manufacturer’s technical findings should be considered together.
Obtain written reasons and preserve technical evidence
Ask the insurer for a written response identifying the policy provision and findings relied upon. Keep expert and workshop reports, photographs, towing records and maintenance history. Consider preservation of evidence before vehicle data are erased or significant parts disposed of. Follow manufacturer and authorised workshop guidance on safety.
Choose the appropriate dispute route
A documented application to the insurer makes the claim and response clear. Insurance arbitration or litigation depends on participation requirements, the nature of the dispute and procedural conditions. If a separate defect claim against the manufacturer or seller arises, assess its relationship with the insurance claim and avoid recovering the same loss twice.
How to organise your application file
Set out events chronologically and match each payment, instruction and reply to its record. Keep original files and capture screenshots with dates and URLs. Retain proof of delivery for written applications. If a statement changes, preserve the earlier version as well. Avoid publishing identity and account information on public channels.
Frequently asked question
What is needed to review an electric-car insurance refusal?
Prepare the policy and special terms, written refusal, damage photographs, workshop report, battery diagnosis and assessment records together. Set out the water exposure, technical fault and stated refusal reason on one timeline.
Safety and technical evidence after an electric vehicle flood
Do not attempt to start or charge a flooded electric vehicle. Arrange qualified recovery, transport and inspection; this article is not a battery intervention manual. Where safe, record water level, location, warning messages and recovery time. Preserve the workshop intake, diagnostic output and photographs of dismantled parts so that later explanations can be checked against the initial findings.
Battery replacement, warranty and total loss are separate questions
Water exposure does not establish that the entire battery must always be replaced or that the car is automatically a total loss. An expert should explain cell, module, connection, insulation and control-system findings, the proposed repair’s safety and the relevant manufacturer procedure. A warranty refusal and a kasko coverage decision arise from different legal relationships. Obtain both reasons in writing rather than treating one refusal as proof of the other. Classification as heavy damage or total loss is also distinct from calculating the insurance payment.
Notification and a coordinated claim plan
Kasko General Conditions B.1.1 provides for notification no later than five working days after learning of the insured event. Notify promptly once safe and retain the submission record; the effect of delay depends on the circumstances. Assemble the policy and endorsements, diagnostic report, recovery invoice, photographs and insurer’s written response. Pre-loss market value, battery repair cost and any salvage must be itemised separately. Coordinate potential insurance, car-park and public-authority claims without recovering the same loss twice. For an initial enquiry send a short summary and relevant dates; provide documents only when requested by our lawyers through the specified channel.
DISCUSS YOUR CASE
Discuss your electric vehicle’s flood and battery damage
We can review the technical findings, warranty and insurance decisions, and the proposed loss calculation to assess your options under Turkish law.
A brief summary and important dates are enough for an initial enquiry. Send documents only when requested by our lawyers, through the channel they specify. Do not share passwords, one-time codes or wallet keys.
Related guides
- Flooded Car in Türkiye: Kasko Notification, Evidence and Payment
- Uninsured Flood-Damaged Car: Claims Against Public Authorities in Türkiye
- Flood Total Loss: Market Value, Salvage and Settlement Releases in Türkiye
- Kasko Refuses Flood Damage: Arbitration, Mediation and Court Options
- Car Flooded in a Car Park, Residential Complex or Mall: Who May Be Liable?
Sources and legislation
Insurance Association of Türkiye: Property Insurance General Conditions
Insurance Arbitration Commission: Applications and information
Related reading
Insurance & Vehicle Diminished Value
Loss of vehicle use after an accident: replacement cars and reasonable repair time
Updated on 15 October 2026. General information under Turkish law. Available remedies and deadlines depend on the particular records. No outcome or recovery is guaranteed. The image is illustrative.